 Writers
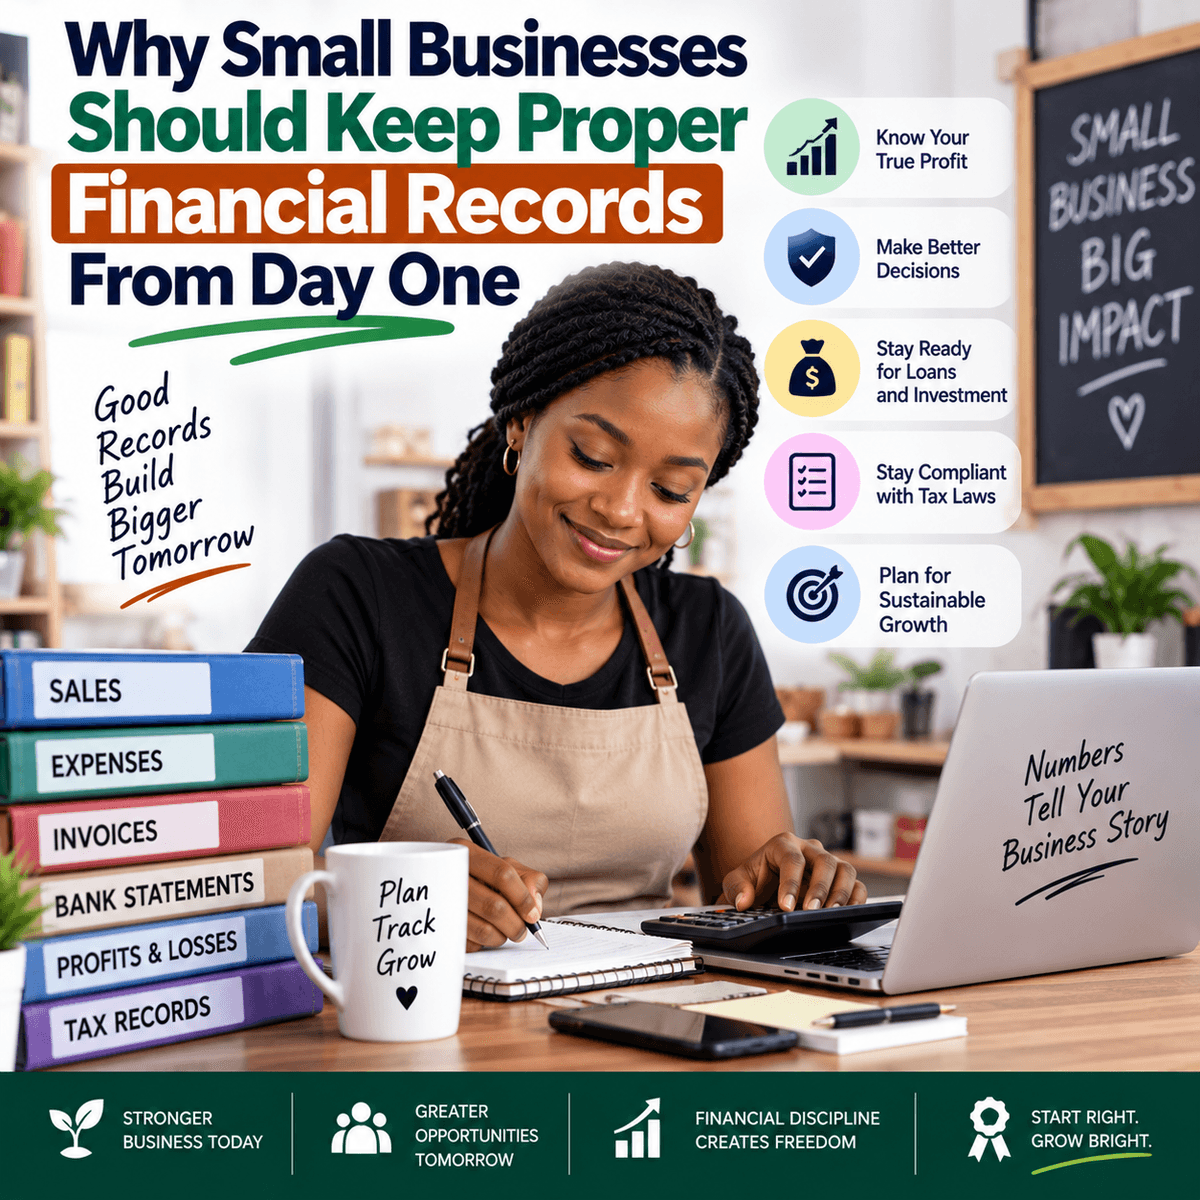
Starting a small business often comes with many demands at the same time. The owner has to find customers, buy goods or materials, promote the business, deliver products, answer customer questions and make sure there is enough money to keep operating. With so much to do, keeping proper financial records can seem like something that can wait until the business becomes bigger. Some owners depend on memory because they believe their business is still small enough to remember every transaction. Others look at the balance in their bank account and use it to decide whether the business is doing well. This approach can create problems because the amount of money in an account does not always show the true state of a business. A business may receive ₦500,000 in customer payments during a month, but that does not mean it made ₦500,000 in profit. The owner may have spent ₦300,000 buying stock, ₦50,000 on transport and delivery, ₦30,000 on electricity and internet, and another amount on rent, wages, repairs or marketing. Some customers may also owe the business, while the business may owe suppliers. Without records, it becomes difficult to put all these figures together and know what is really happening. Good financial records simply mean keeping clear information about the money that enters and leaves the business. This includes sales, purchases, operating costs, money owed by customers, money owed to suppliers and other financial transactions. You do not need to wait until you have several employees or millions of naira in sales before doing this. In fact, starting when the business is small can make the habit easier to maintain as the business grows.
One of the main reasons to keep records is to know whether your business is actually making money. Many business owners focus heavily on sales because sales are easy to see. When customers are buying regularly and money is entering the account, it can feel as though the business is performing well. But sales and profit are not the same thing. Suppose you buy 100 items at ₦4,000 each. Your stock costs ₦400,000. You then sell all the items for ₦6,000 each, giving you total sales of ₦600,000. Looking only at sales might make it appear that you made ₦600,000. However, the goods themselves cost ₦400,000, leaving ₦200,000 before you consider other costs. If you spent ₦50,000 on delivery, ₦30,000 on advertising, ₦20,000 on packaging and ₦40,000 on other business expenses, the amount left becomes much smaller. Records help you see these differences. They can also help you identify which products or services make money and which ones do not. You may discover that your most popular product brings very little profit because its costs are high. Another product may sell less often but leave a better amount after costs. Without records, you may continue putting most of your money into the wrong part of the business simply because it generates more sales. Accurate records also help you notice changes. If transport costs suddenly rise or the cost of materials increases each month, you can see the effect and decide whether you need to change your price, find another supplier, reduce waste or take another step. Business decisions become easier when you have figures to examine instead of relying only on memory or feelings.
Proper records can also help a small business manage its cash more carefully. A business can make a profit on paper and still struggle to pay its bills if money does not arrive when it is needed. For example, imagine that you supply goods worth ₦500,000 to customers on credit. You have made sales, but if those customers will not pay for another 30 or 60 days, you may not have enough cash to buy new stock today. At the same time, your suppliers may expect payment immediately. If you do not keep records of who owes you, how much they owe and when payment is due, you can easily lose track of outstanding money. The same applies to money your business owes. You should know which bills are due, when they must be paid and whether the business has enough money to meet them. Records can also help reduce unnecessary spending. When expenses are written down, you can review them and see where money is going. You may discover that you are paying for services you hardly use, spending too much on delivery or making frequent small purchases that add up to a large amount each month. Small expenses can be difficult to remember, especially when you pay in cash. Record them as they happen and keep receipts or other proof where possible. You can use a notebook, spreadsheet, bookkeeping app or accounting software depending on the size and needs of the business. The tool matters less than keeping complete and accurate information. Set aside time each day or week to update the records instead of waiting for several months and trying to remember old transactions. Once records become part of your normal business routine, managing them becomes much easier.
Good records become even more useful when you want to grow the business or seek outside funding. Growth costs money. You may want to buy equipment, increase your stock, employ workers, rent a larger space, open another location or enter a new market. Before making such a decision, you need to know whether the business can afford it. Financial records can help you compare past income and expenses and estimate how much money the business may have available. They can also show whether sales have been growing steadily or whether one unusually good month has created a false impression of growth. If you approach a bank, investor or other possible source of finance, clear records can help you explain how the business performs and how you plan to use additional money. A lender or investor may want more detailed documents than your normal daily records, but organised information gives you a better starting point. Proper records can also make it easier to work with an accountant and meet tax and other financial duties that apply to your business. The exact records and reports you need will depend on the type, size and legal form of your business, so seek current professional advice when necessary. Records can also protect the business when disagreements occur. If a customer says payment has already been made or a supplier claims that you still owe money, invoices, receipts and payment records can help you check what happened. The same applies when you employ staff or work with business partners. Clear records reduce the need to depend on memory when money is involved.
Keeping financial records does not have to become difficult simply because the term sounds formal. Start with the basics and improve your system as your business grows. Record every sale, whether the customer pays by cash, transfer or another method. Record every business expense and state clearly what you paid for. Keep business money separate from personal money as much as possible so that personal purchases do not make your records confusing. Keep invoices, receipts and other useful documents in an organised way, whether you store them on paper or in a secure digital form. Check your records against your bank transactions and cash regularly so that you can find mistakes early. At the end of each month, review the figures and ask a few basic questions: How much did the business sell? How much did it spend? Which expenses increased? How much do customers still owe? How much does the business owe? How much money remains available? What appears to be working well, and what needs attention? As the business becomes larger or more complex, consider getting help from a qualified accountant or bookkeeper. You do not have to understand every part of accounting before you begin keeping useful records. What matters is developing the habit of knowing where your business money comes from and where it goes. A small business owner who keeps good records has better information for setting prices, controlling costs, planning purchases, following up on debts and deciding when to grow. Do not wait until missing money, unpaid bills or confusing accounts force you to start. Build the habit from the first day of the business and allow your records to become one of the tools you use to make sound business decisions.