 Writers
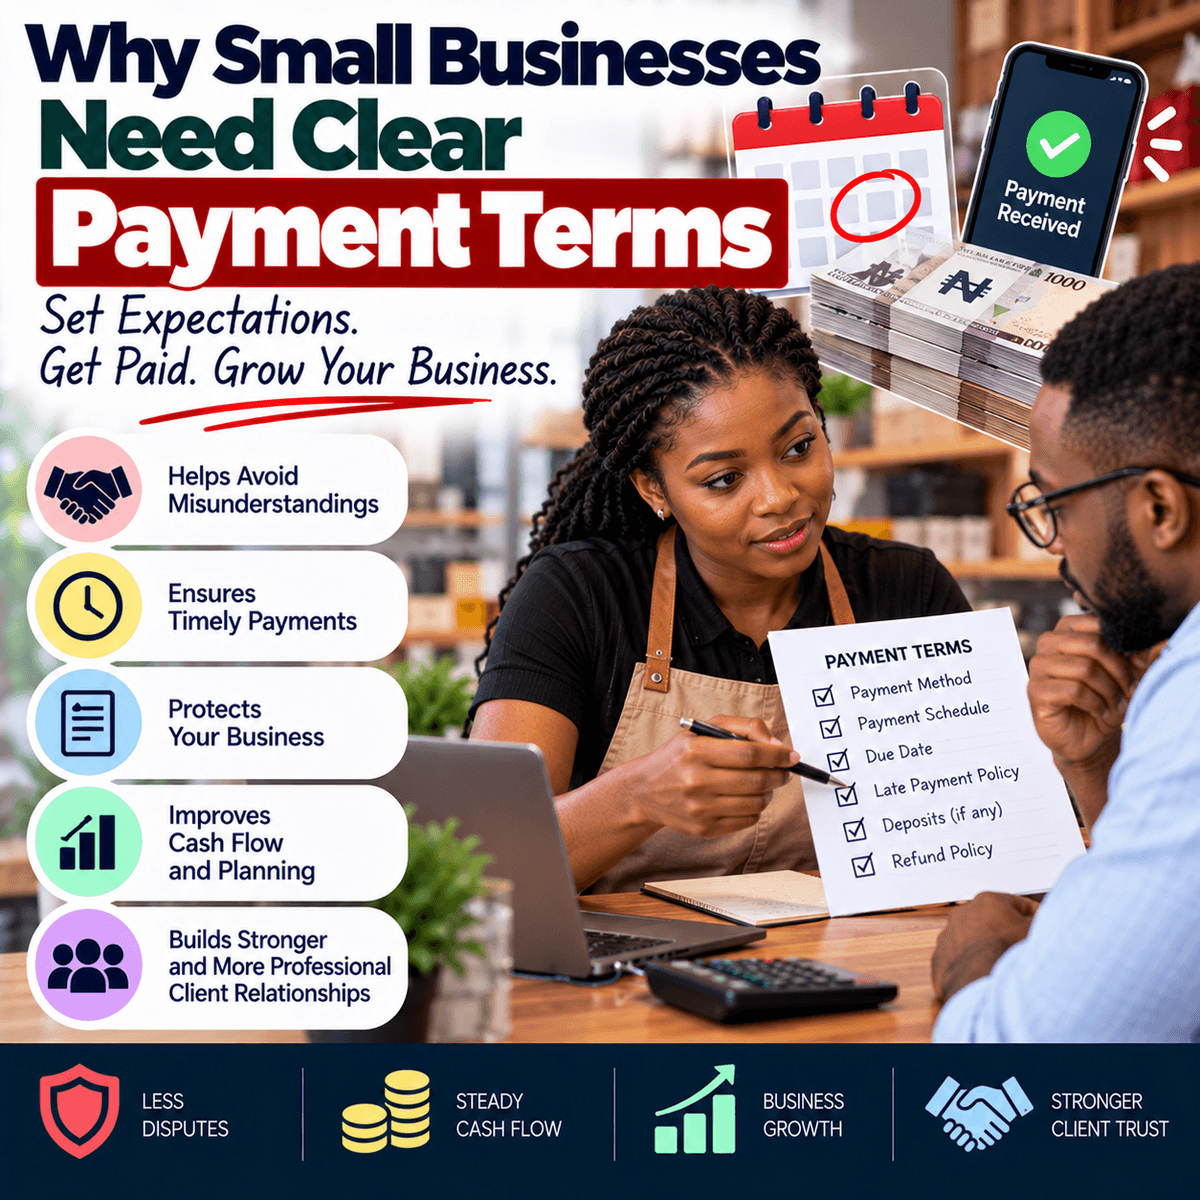
Making a sale is important for every small business, but a sale does not fully help the business until payment is received. Many small businesses focus heavily on finding customers, promoting their products and delivering good service but pay less attention to how and when customers are expected to pay. This can create serious problems, especially when goods or services are supplied before full payment is received. A customer may promise to pay within a few days, but without a clear agreement, a few days can become several weeks or even months. Meanwhile, the business still has expenses to meet. It may need to pay workers, replace stock, buy materials, pay for transport, settle rent, purchase fuel or data and meet other operating costs. This is why every small business needs clear payment terms. Payment terms simply explain the conditions under which a customer is expected to pay. They can state the total amount due, whether a deposit is required, when the balance must be paid, the accepted payment methods and what happens if payment is delayed. These terms do not need to be complicated, but they should be communicated before the business commits significant time, money or resources to the transaction. A business owner should not assume that a customer understands the expected payment arrangement simply because it seems obvious. One person may think payment is due immediately after delivery, while another may assume they have thirty days to pay. Clear terms remove much of this uncertainty. They also make the business look organised and professional. Customers know what is expected of them, while the business has a clear basis for following up when payment is overdue. Good payment terms are therefore not about being difficult with customers. They are about creating a fair understanding before money becomes a source of disagreement.
Clear payment terms become even more important when a business allows customers to pay later. Giving credit can sometimes help a business attract or retain customers, particularly when dealing with other businesses, but it also transfers some financial risk to the seller. The business has already provided value while waiting for its money. Before offering credit, a small business should decide who qualifies, how much credit can be given and how long customers have to pay. It may not be wise to give every new customer a large amount of credit simply because they promise to pay later. A business can start with smaller transactions and build confidence based on the customer's payment history. For larger jobs, requesting a deposit before work begins can reduce the amount of money the business has to provide from its own pocket. For example, a service provider who needs to buy materials before starting a project may require an initial payment that covers part of those costs. The remaining amount can then be tied to agreed stages of the work or to completion. Whatever arrangement is chosen should be explained clearly before the work begins. The customer should know the price, the amount required upfront, the due dates and the payment method. If there are conditions for refunds, cancellations, changes to the work or additional requests, these should also be made clear where relevant. Written terms are usually better than depending entirely on verbal discussions because people can remember conversations differently. A quotation, invoice, order form, contract or even a clear written message can provide a record of what was agreed. For significant transactions, appropriate professional or legal advice may also be necessary. The goal is to prevent a situation where the business completes the work only to discover that the customer had a completely different understanding of when payment was due.
Poor payment management can create cash flow problems even when a business appears to be making good sales. Consider a small business that sells ₦1 million worth of goods during a month but collects only ₦400,000 because most customers have been allowed to pay later. On paper, the sales figure may look encouraging, but the business cannot use unpaid invoices to settle every immediate expense. If suppliers require payment, workers expect their wages and stock needs to be replaced, the business may quickly run short of cash. This shows why revenue and available cash are not always the same thing. A profitable-looking business can still struggle if customers take too long to pay. Clear payment terms help reduce this problem by creating a predictable collection process. The business should also keep proper records of invoices and payments rather than relying on memory. Each credit sale should show the customer, amount, date, due date, amount already paid and outstanding balance. Regularly reviewing these records makes it easier to identify overdue accounts early. Waiting several months before checking who owes the business makes collection more difficult. A simple spreadsheet, accounting application or organised record book may be enough for a very small business, depending on its size and needs. The important thing is that the information is accurate and regularly updated. Business owners should also separate money that has actually been received from money customers have only promised to pay. Expected payments can be considered when planning, but essential expenses should not be based entirely on the assumption that every customer will pay exactly when expected. Keeping a close watch on amounts owed gives the owner a clearer picture of the business's real financial position.
How a business follows up on unpaid invoices is also important. Some owners feel uncomfortable asking customers for money because they fear damaging the relationship. However, requesting payment according to an agreed schedule is a normal part of doing business. The process can remain polite and professional. A reminder can be sent shortly before the due date, especially for larger invoices. If payment becomes overdue, contact the customer promptly and refer to the agreed amount and due date. Avoid turning the first reminder into an argument. Sometimes a payment is delayed because an invoice was overlooked, sent to the wrong person or needs an internal approval. A clear reminder may solve the problem quickly. If the customer is experiencing a genuine difficulty, the business can decide whether a reasonable payment arrangement is appropriate, but any new agreement should also be documented. At the same time, businesses should recognise repeated patterns. A customer who consistently ignores payment dates, makes promises that are not kept or accumulates larger debts may present a growing risk. Continuing to provide more goods or services on credit can make the problem worse. The business may need to pause further credit or require advance payment before accepting another order. For serious unpaid debts, appropriate professional advice may be necessary depending on the amount, agreement and local legal requirements. Business owners should also make payment easy for genuine customers. Provide correct bank or payment details, issue invoices promptly and clearly identify the payment reference where needed. When a payment is received, update the customer's account and provide a receipt or confirmation where appropriate. A well-organised process makes it easier for customers to pay and easier for the business to identify those who have not.
Every small business should develop payment terms that match the way it operates rather than copying another company's rules without considering its own situation. A retail business where customers pay before leaving the shop has different needs from a consultant who completes projects over several months. A contractor buying expensive materials may need a larger deposit than a business providing a service with few upfront costs. Start by looking at your normal transactions and identifying where payment delays create problems. Decide when payment should be made, whether deposits are necessary, how long credit customers will have to pay and what payment methods you accept. Put these terms in writing and communicate them before the transaction reaches a stage where changing the arrangement becomes difficult. Make sure invoices contain the correct customer information, description of the goods or services, amount due, payment details and due date. Keep accurate records and review outstanding payments regularly. When customers pay on time, acknowledge the payment and maintain the relationship. When payments become overdue, follow up consistently instead of hoping the customer will eventually remember. Most importantly, do not allow the desire to make more sales to cause the business to accept payment arrangements that place its survival at risk. A large order is not automatically a good order if the business spends heavily to fulfil it and then struggles for months to collect the money. Clear payment terms help both sides understand their responsibilities from the beginning. For a small business with limited cash and resources, that clarity can make the difference between simply recording sales and actually having enough money available to keep the business operating.