 Writers
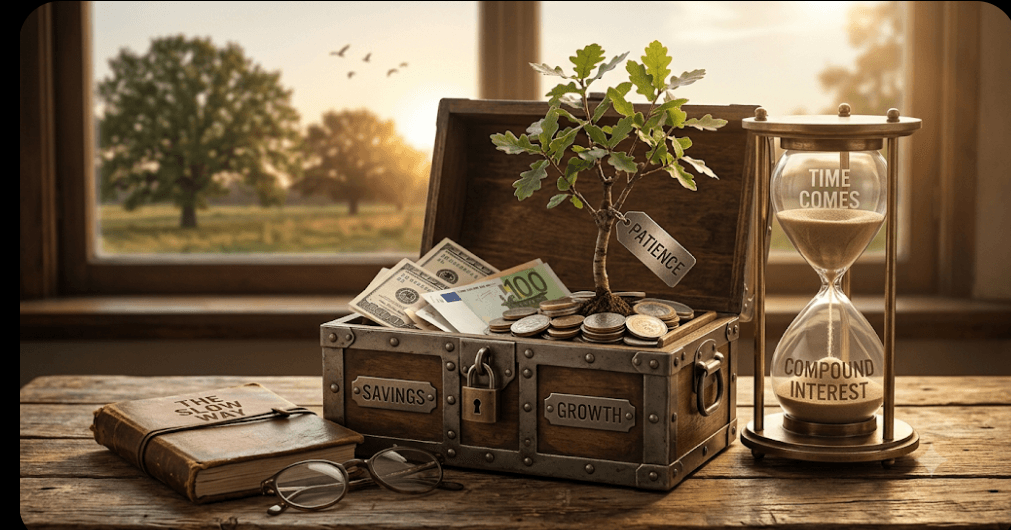
Every few months, a new shortcut to wealth goes viral. A hot stock, a trending crypto coin, a course promising financial freedom in 90 days. Most people who chase these shortcuts end up where they started, or worse.
There is a quieter alternative: "get rich slow." It lacks the excitement, but it is more reliable. Here is what it means, why it works, and where it falls short.
What "Get Rich Slow" Actually Means
"Get rich slow" is the practice of building wealth through consistent saving, steady investing, and time, rather than through one big win. It rests on three ideas:
Spend less than you earn. Nothing else works without this.
Invest the difference regularly, usually in diversified, low-cost funds.
Leave it alone for decades so growth can compound.
Nothing here is secret. The difficulty is not knowledge but behavior: doing simple things consistently when nobody is applauding.
The Math Behind the Patience
The engine of this approach is compound growth, where your returns start earning returns of their own. Early on, it feels painfully slow. Later, it accelerates.
Consider a hypothetical example. Say you invest $300 a month and earn an average of 7% annually. That return is an assumption for illustration, not a guarantee, and real markets rise and fall unevenly.
After 10 years: roughly $52,000, of which $36,000 is your own contributions.
After 30 years: roughly $366,000, of which only $108,000 is your own money.
In the 30-year scenario, most of the final balance comes from growth rather than deposits. That is why time matters more than almost any other variable.
The Cost of Waiting
Now suppose you wait 10 years to start, investing the same $300 a month for only 20 years at the same assumed return. You would end up with roughly $156,000, less than half the 30-year result. The decade you skipped cost more than $200,000 in this example.
You do not need a large amount to begin. You need to begin.
What "Get Rich Slow" Does Not Promise
An honest look at this strategy requires acknowledging its limits.
It is not guaranteed. Markets decline, sometimes sharply, and sometimes for years. Diversification and a long time horizon reduce risk but do not eliminate it.
It is not fast. If you need a large sum in two or three years, investing in the market is not the right tool. Short-term goals call for savings, not investments.
It does not work without income room. For someone struggling to cover basic expenses, "invest more" is unhelpful advice. In that situation, the first steps are raising income, reducing costs, or building an emergency cushion.
It may not make you "rich" by every definition. For many people, the realistic outcome is financial security: a comfortable retirement, freedom from paycheck-to-paycheck stress, and options. That is a worthy goal, but it is not a yacht.
Four Habits That Make It Work
1. Build a Buffer First
Before investing, set aside an emergency fund, commonly three to six months of essential expenses. Without one, a car repair or job loss can force you to sell investments at a bad time.
2. Automate Everything
Set up automatic transfers on payday. When saving requires a decision every month, it eventually loses. When it happens automatically, it becomes background noise.
3. Keep Costs Low
Fees quietly erode returns over long periods. A fund charging 1% a year takes far more of your growth over 30 years than one charging 0.1%. Compare expense ratios before you commit.
4. Raise Your Contributions Over Time
Each time you get a raise, increase your monthly contribution. Even a small bump matters. If you start at $300 and grow to $500 over the years, your outcome improves considerably without a dramatic lifestyle change.
Common Mistakes to Avoid
Reacting to headlines. Selling during a downturn locks in losses. Investors who panic often miss the recovery.
Chasing performance. Last year's winning fund or asset is not a promise about next year.
Ignoring debt. High-interest debt, such as credit card balances, can outpace your investment returns. Paying it down is often the smarter first move.
Waiting for the "perfect" time. No one reliably predicts market peaks and bottoms. Regular investing removes the need to guess.
Overcomplicating it. A simple, diversified approach you stick with beats a complicated one you abandon.
A Simple Way to Start This Month
You do not need to overhaul your finances today. Try this:
Calculate your monthly essentials to see what you can realistically set aside.
Open a savings account for your emergency fund and automate a deposit.
If you have access to an employer retirement plan, find out whether there is a matching contribution. It is one of the few genuine bonuses in personal finance.
Choose a low-cost, diversified fund through a reputable provider and automate a monthly contribution.
If your situation is complex, involving taxes, business income, or significant debt, consider speaking with a qualified financial professional. This article is educational and not personalized advice.
"Get rich slow" is not glamorous, and it will not make a good social media video. But its logic is sound: consistent contributions, low costs, and time do most of the work. The biggest advantage you have is not a clever strategy or a perfect market call. It is the number of years ahead of you.
You cannot get those years back once they pass, so start with what you can afford today, automate it, and let time do its job.